Four US corporate organizational models

A range of organizational structures exists for U.S.-based enterprises seeking to balance profit, purpose, and public accountability. Traditional corporations, benefit corporations, Certified B Corporations, and not‑for‑profit [501(c)(3)] organizations each embody distinct legal frameworks, governance expectations, and operational constraints. Understanding how these forms differ—particularly in purpose requirements, accountability mechanisms, transparency obligations, and tax treatment—provides a useful foundation for evaluating which structure best aligns with an organization’s mission and strategic goals.
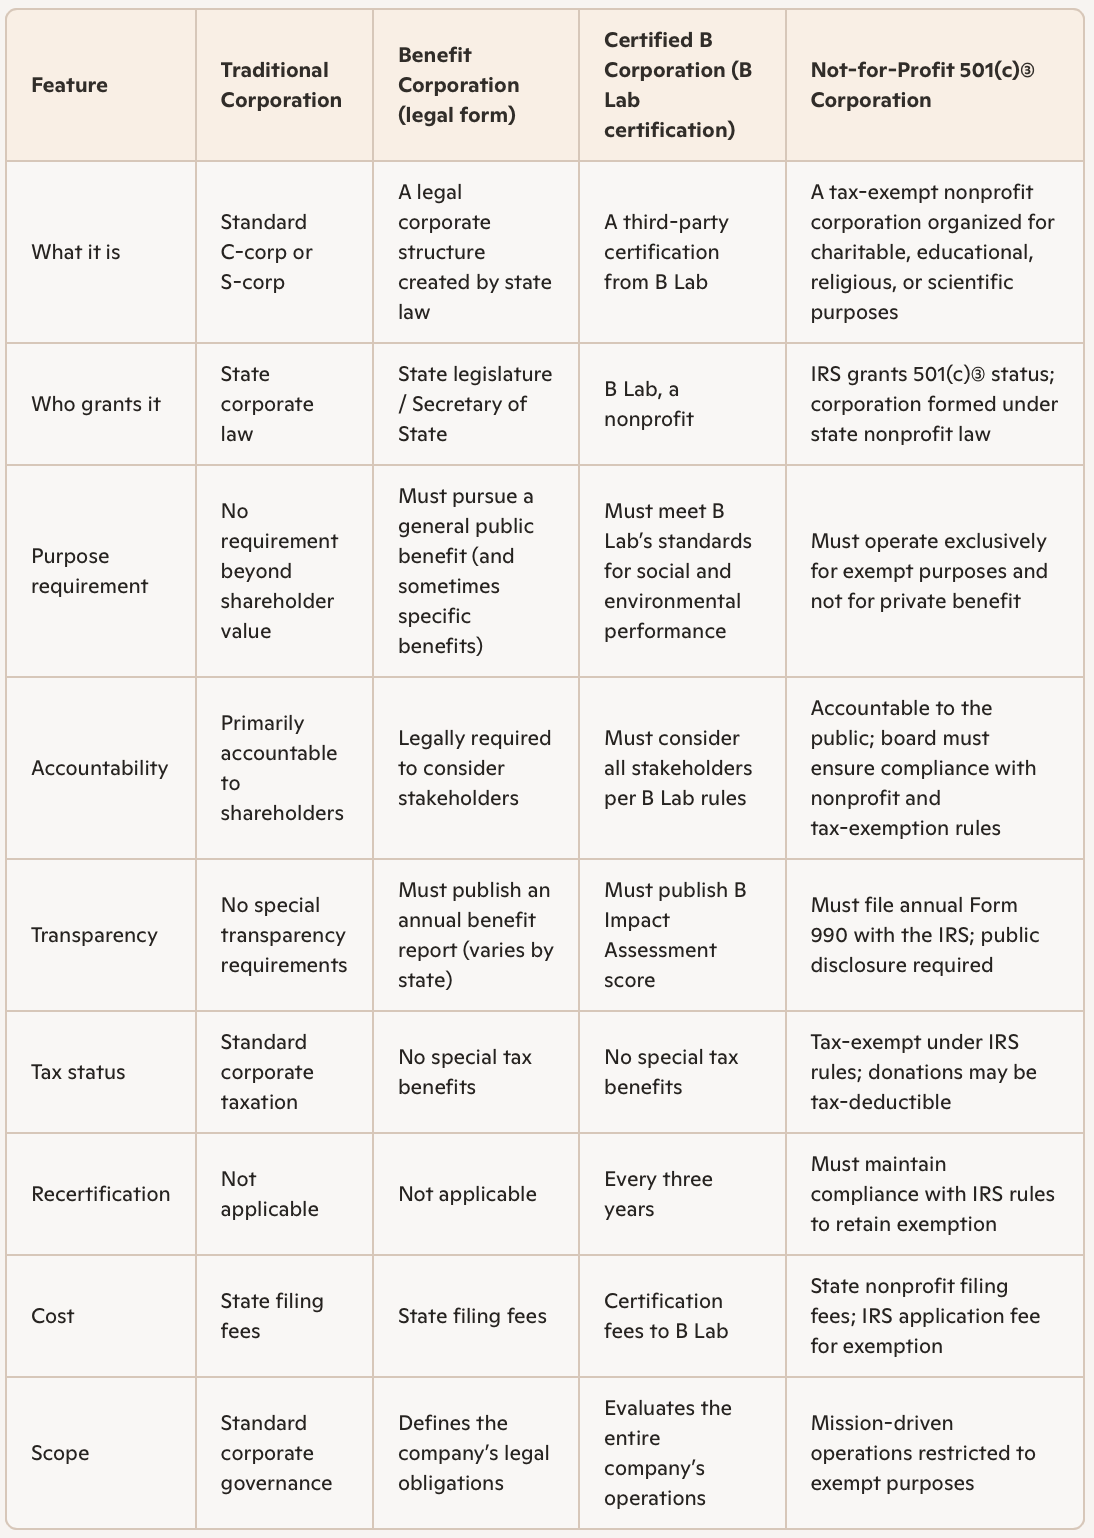
A traditional corporation—whether organized as a C‑corp or S‑corp—operates under standard corporate law. Its primary legal obligation is to act in the best interests of shareholders, typically interpreted as maximizing shareholder value. Traditional corporations have no statutory requirement to consider broader stakeholder interests, although many do so voluntarily. They also have no special transparency obligations beyond standard financial reporting and regulatory compliance. Traditional corporations represent the default model for most for‑profit enterprises and are taxed according to standard corporate tax rules.
A benefit corporation, by contrast, is a legal corporate form created by state statute. Unlike B Certification, which is voluntary and administered by a nonprofit, benefit corporation status is embedded in the company’s governing documents and enforceable under state law. A benefit corporation must pursue a general public benefit and, in some states, may also designate specific public benefits. Directors are legally required to consider the interests of stakeholders beyond shareholders. Transparency is built into the structure through the requirement to publish an annual benefit report. However, benefit corporation status does not confer tax advantages; it simply modifies the governance obligations of a for‑profit entity.
A certified B corporation is a for‑profit company that voluntarily undergoes a third‑party evaluation by B Lab to demonstrate high standards of social and environmental performance, accountability, and transparency. Certification does not alter the company’s legal structure; it overlays an external standard on top of whatever corporate form the business already has. To maintain certification, the company must periodically recertify and publicly disclose its impact score. The central idea is that the company commits to operating in a way that benefits all stakeholders—workers, communities, customers, and the environment—while still pursuing profit.
A not‑for‑profit [501(c)(3)] corporation is fundamentally different from all three for‑profit forms. It is organized under state nonprofit law and must operate exclusively for charitable, educational, religious, scientific, or similar exempt purposes. Unlike for‑profit entities, a 501(c)(3) cannot distribute profits to private individuals or shareholders; any surplus must be reinvested in the organization’s mission. The IRS grants federal tax‑exempt status, and donations may be tax‑deductible. Transparency is enforced through the annual Form 990 filing, which must be made publicly available. Governance is mission‑driven, and the board is responsible for ensuring compliance with nonprofit and tax‑exemption requirements.
Taken together, these four structures represent distinct approaches to purpose, accountability, transparency, and taxation. Traditional corporations prioritize shareholder interests within a flexible governance framework. Benefit corporations and Certified B Corporations both integrate social and environmental considerations into business operations, but one does so through legal structure and the other through voluntary certification. Not‑for‑profit[ 501(c)(3)] corporations operate under a completely different paradigm, one centered on public benefit and tax‑exempt mission‑driven activity rather than profit generation.
Comparative table
Sources
Traditional Corporations
General corporate law references (state‑level corporate statutes) No single URL is authoritative because corporate law varies by state, but the following provides a widely used overview: https://www.nolo.com/legal-encyclopedia/corporations (
Supports: Shareholder‑primacy norms, standard governance, taxation, and reporting requirements.
Certified B Corporations and B Lab
B Lab – “What’s the difference between a Certified B Corp and a benefit corporation?” https://www.bcorporation.net/en-us/faq/whats-difference-between-certified-b-corp-and-benefit-corporation/
Supports: Definition of Certified B Corporations, distinction from benefit corporations, stakeholder accountability, certification requirements.
Legal Distinctions Between Benefit Corporations and B Corps
Morgan Lewis – “Benefit Corporations and Certified B Corps: What’s the Difference?” https://www.morganlewis.com/-/media/files/special-topics/vcpefdeskbook/impact-investing/benefit-corporations-and-certified-b-corps-whats-the-difference.pdf
Supports: Legal structure of benefit corporations, fiduciary duties, stakeholder governance, and differences from B Lab certification.
UpCounsel – “Benefit Corporation vs B Corp: Legal vs Certified” https://www.upcounsel.com/benefit-corporation-vs-b-corp
Supports: Formation requirements, reporting obligations, certification process, and the fact that B Corps can take many legal forms.
Not‑for‑Profit [501(c)(3)] Corporations
IRS – “Exemption Requirements – 501(c)(3) Organizations” https://www.irs.gov/charities-non-profits/charitable-organizations/exemption-requirements-501c3-organizations
Supports: Tax‑exempt status, operational restrictions, public‑benefit purpose, IRS Form 990 transparency requirements.